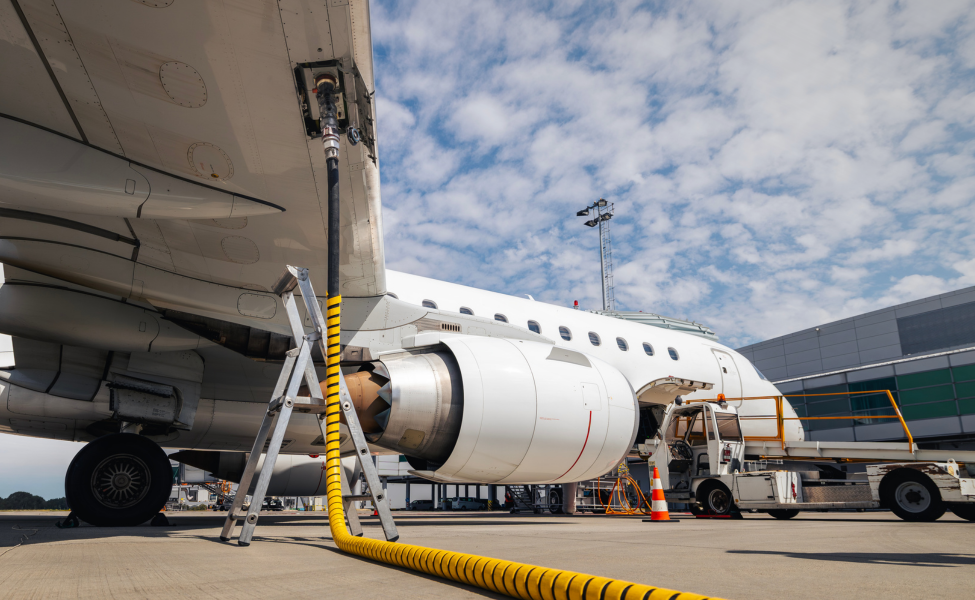
The European Commission has initiated a partial interim review of the anti-dumping and anti-subsidy measures affecting sustainable aviation fuel from the USA, as part of the trade defence measures currently applicable to imports of biodiesel originating in the United States.
The proceedings are set out in Notices C/2026/4087 and C/2026/4088, concerning the anti-subsidy and anti-dumping measures respectively.
The reviews are specifically limited to the product scope. Their purpose is to determine whether certain sustainable aviation fuels (SAF) derived from hydrotreated esters and fatty acids, known as HEFA-derived SAF, should continue to be included within the definition of the product subject to the existing measures.
For companies involved in the import or use of sustainable aviation fuel in the European Union, the outcome could therefore have significant customs and cost implications.
Anti-dumping and anti-subsidy measures on biodiesel from the USA
The measures under review currently apply to certain biodiesel products originating in the United States.
The product concerned includes fatty-acid mono-alkyl esters and/or paraffinic gasoil obtained through synthesis and/or hydrotreatment, of non-fossil origin, either in pure form or in certain blends.
The products covered by the current measures are classified under several CN and TARIC codes, including:
- ex 1516 20 98 — TARIC 1516 20 98 29
- ex 1518 00 91 — TARIC 1518 00 91 29
- ex 1518 00 95 — TARIC 1518 00 95 33
- ex 1518 00 99 — TARIC 1518 00 99 29
- ex 2710 19 11 — TARIC 2710 19 11 10
- ex 2710 19 15 — TARIC 2710 19 15 10
- ex 2710 19 21 — TARIC 2710 19 21 10
- ex 2710 19 25 — TARIC 2710 19 25 10
- ex 2710 19 29 — TARIC 2710 19 29 10
- ex 2710 19 42 — TARIC 2710 19 42 29
- ex 2710 19 44 — TARIC 2710 19 44 29
- ex 2710 19 46 — TARIC 2710 19 46 29
- ex 2710 19 47 — TARIC 2710 19 47 29
- ex 2710 20 11 — TARIC 2710 20 11 29
- ex 2710 20 16 — TARIC 2710 20 16 29
- ex 3824 99 92 — TARIC 3824 99 92 14 and 3824 99 92 17
- 3826 00 10
- ex 3826 00 90 — TARIC 3826 00 90 19
The CN and TARIC classification must always be assessed together with the characteristics and composition of the goods concerned.
Why are sustainable aviation fuels being reviewed?
The central issue in both reviews is whether HEFA-derived sustainable aviation fuels should remain within the scope of the existing biodiesel measures.
HEFA-derived SAF consists of paraffinic gasoils of non-fossil origin obtained through synthesis and/or hydrotreatment, either in pure form or as part of a blend.
These sustainable aviation fuels were included within the original product scope and are currently covered under several CN codes in heading 2710.
The review therefore does not concern the introduction of a completely new trade defence measure on SAF.
Instead, the European Commission is examining whether this particular type of sustainable aviation fuel should be excluded from the definition of the product already subject to anti-dumping and anti-subsidy measures.
Which HEFA-derived SAF products are covered by the review?
The sustainable aviation fuels specifically considered in the review currently fall under the following classifications:
- ex 2710 19 11 — TARIC 2710 19 11 10
- ex 2710 19 15 — TARIC 2710 19 15 10
- ex 2710 19 21 — TARIC 2710 19 21 10
- ex 2710 19 25 — TARIC 2710 19 25 10
- ex 2710 19 29 — TARIC 2710 19 29 10
These codes cover the HEFA-derived SAF that formed part of the original product definition.
For importers, however, tariff classification alone is not sufficient. The composition, production process, non-fossil origin and intended use of the product may also be relevant when determining whether a specific shipment falls within the scope of the measures.
Possible exclusion of HEFA-derived SAF from the product scope
The purpose of the partial interim review is to assess whether there are sufficient grounds to exclude HEFA-derived SAF from the existing product scope.
The review is based on the argument that sustainable aviation fuels of this type constitute a distinct product compared with other products originally targeted by the trade defence measures.
Differences may relate to their characteristics, production processes, end uses and regulatory treatment.
The European Commission will assess these factors before determining whether the current scope of the measures should be amended.
Importantly, the opening of the review does not mean that HEFA-derived SAF has already been excluded.
Until the European Commission adopts a final decision, importers should continue to assess the existing trade defence measures when importing products that fall within the current scope.
Customs impact for EU importers of sustainable aviation fuel
The outcome of the review could be particularly significant for companies importing sustainable aviation fuel from the United States into the European Union.
If the European Commission ultimately decides to exclude HEFA-derived SAF from the product definition, the customs treatment of certain imports could change.
Until that decision is adopted, companies should continue to pay close attention to the applicable CN and TARIC classification, product composition, customs origin and existing anti-dumping and anti-subsidy measures.
The distinction between conventional biodiesel products and sustainable aviation fuel may therefore become increasingly important from a customs compliance perspective.
Why the correct TARIC classification of SAF matters
Trade defence measures in the European Union are closely linked to the tariff classification and origin of imported goods.
Companies importing sustainable aviation fuel should therefore ensure that the product description used in their customs documentation accurately reflects the characteristics of the goods.
Particular attention should be paid to the relevant CN and TARIC code, the production process used, whether the fuel is of non-fossil origin, whether it is imported in pure form or as part of a blend and whether it qualifies as HEFA-derived SAF.
A detailed review of these elements can help determine the trade defence measures applicable when the goods are released for free circulation.
Anti-dumping and anti-subsidy measures are separate proceedings
Although the two reviews concern the same product scope, they relate to two different types of EU trade defence measures.
Notice C/2026/4087 concerns the partial interim review of the anti-subsidy measures applicable to biodiesel originating in the United States.
Notice C/2026/4088 concerns the partial interim review of the anti-dumping measures applicable to the same imports.
Both proceedings examine the potential exclusion of HEFA-derived sustainable aviation fuels from the product scope.
For importers, this means that any analysis of the eventual impact should consider both the anti-dumping and anti-subsidy frameworks.
How long will the SAF review take?
The European Commission states that the investigations should normally be concluded within 12 months from the publication of the Notices.
In any event, they must be completed no later than 15 months from the publication date.
Companies importing or using HEFA-derived sustainable aviation fuels should therefore monitor the proceedings and any subsequent decisions adopted by the European Commission.
Changes to the product scope could directly affect the application of trade defence duties to future imports.
What should SAF importers review during the investigation?
Companies involved in importing sustainable aviation fuel from the United States should assess their current operations while the reviews remain open.
Key elements include the tariff classification applied to the product, its technical composition, its production process, its customs origin, the supplier and manufacturer involved and the trade defence duties currently applicable.
Businesses should also maintain sufficient product documentation to demonstrate whether a fuel meets the characteristics of the HEFA-derived SAF being considered in the European Commission’s review.
This information may become particularly relevant if the scope of the existing measures is subsequently amended.
Customs advice on sustainable aviation fuel and EU trade defence measures
The review of anti-dumping and anti-subsidy measures affecting sustainable aviation fuel from the USA highlights the importance of analysing tariff classification, customs origin and trade defence measures together.
The possible exclusion of HEFA-derived SAF could have a direct impact on the customs treatment and import costs of certain sustainable aviation fuels entering the European Union.
Arola’s customs department remains available to assist companies in assessing the impact of anti-dumping and anti-subsidy measures, reviewing TARIC classifications and analysing the customs requirements applicable to imports of sustainable aviation fuel.